
By Brian Sullivan, CFP® Professional, Primary Financial Advisors
TL;DR: Scenario planning is the process of mapping out the potential financial implications of your biggest decisions and most pressing what-ifs, before you make them.
A CERTIFIED FINANCIAL PLANNER® Professional can model multiple versions of your future simultaneously, showing you how a career change, a health event, or a major life transition would affect your retirement, your taxes, your estate, and your cash flow.
What Is Scenario Planning in a Financial Plan?
Most financial plans are built around a single version of the future. A retirement date. An assumed rate of return. A projected spending level.
What if the timeline shifts, a health event occurs, or a major decision needs to be made sooner than expected? What if you want to explore a different path entirely?
That's where scenario planning comes in.
It’s the process of modeling multiple versions of your future, side by side, so you can see clearly how different decisions and different life events might affect your financial picture.
Rather than asking, "Will my plan work?" scenario planning asks, "Will my plan work under these different circumstances?" It turns abstract what-ifs into concrete numbers.
If you’d like to learn more about what goes into a comprehensive plan before you dive deeper into scenario-based financial plans, read this blog post.
When Do You Incorporate Scenarios into a Financial Plan?
You might benefit from this type of thinking if you are:
Considering selling or transitioning out of a business
Navigating a significant equity event such as an IPO, acquisition, or RSU vesting
Exploring the sale or purchase of real estate
Taking on the care of family members while managing your own retirement timeline
Facing a health diagnosis that changes the financial picture
What Questions Should You Ask Before You Build Out a Scenario?
Before your financial advisor models scenarios, they should have an in-depth conversation with you. Here are a few of the questions a financial advisor might ask:
What does your ideal future look like?
What are the alternatives you're considering or worried about?
What are the key variables in your financial life right now, including your income, assets, debt, expenses, and obligations?
What life events are on the horizon, planned or possible, that could change the picture?
What level of risk are you comfortable with, and what outcomes are simply unacceptable?
What is your timeline? How might this change under different circumstances?
Now let’s look at the types of scenarios that can be built for clients at various life stages.
Scenario Planning for a 55-Year-Old Executive
Scenario One: What could a path to retirement at 60 look like?
Imagine you’re a 55-year-old executive with a spouse and two teenage children.
You own your home.
Based on what you’ve saved, your investments, and the vesting schedule for your equity compensation, it looks as though you can retire at 60 while paying for your children’s education.
But what happens when life introduces other variables?
Scenario Two: What happens if I experience a career shift?
What if you need to leave your corporate position?
Maybe you just want “out”.
Or you’re worried that your position may be eliminated if your company is acquired?
Scenario planning can help you answer questions like:
Should I look for a full-time job or should I start my own consulting practice?
If I want to start my own business, when should I take the leap?
What will my budget and retirement look like if I leave my corporate job now to become an entrepreneur? How will my tax situation change?
Can I still afford to help my kids pay for college?
Scenario Three: How will health issues impact our finances over time?
What if your spouse recently received a serious health diagnosis and their condition could change dramatically in 3-5 years?
Scenario planning can answer questions like:
What if I have to cut back my hours as an employee or consultant to care for my spouse?
What kind of in-home or long-term care can we afford and for how long?
How will our retirement picture and college contributions change with these unexpected expenses?
A financial advisor can help you model all of these things out at once, or they can make projections as your life and needs change.
Scenario Planning for a Couple in Their 70s
Scenario planning isn't only for people who are accumulating wealth throughout their working years.
Imagine you and your spouse are in your 70s.
Suddenly, your partner is diagnosed with Parkinson’s Disease. You know you can’t handle the physical demands of managing household while caring for your spouse.
Several years ago, you and your spouse toured assisted living facilities. You fell in love with one community that’s close to your children and family members. You put your name on the waiting list.
Now that the transition to assisted living is approaching, you want to understand the best way to fund your care while preserving your estate for your children.
You know you’ve worked hard and you’ve saved substantially more than your friends.
On the other hand, long-term care is SO expensive. Will you have to pinch every penny once you move to be able to afford to stay in your preferred community?
This is where scenario planning can really provide clarity and hopefully peace of mind.
Scenario One: How should you manage real estate?
For many people in this stage of life, their home is a significant asset. The concept of what to do with it can be overwhelming. Scenario planning can help you model two paths: selling a home outright vs. renting it and preserving the asset. Each has different implications for your liquid assets, your monthly cash flow, your tax picture, and your estate. Seeing the numbers side by side can help you decide which choice to make.
Scenario Two: What will care cost over time?
Scenario planning can model what your finances would look like if you and/or your spouse need to move from independent or assisted living to a memory care unit or skilled nursing in three, five, or eight years.
That can make a difference if the costs for your chosen long-term care community are similar to what we see in Northern New England where a higher-end facility in 2026 can cost ~$10,000 a month per person for assisted living for one person and ~$18,000 a month per person for skilled nursing.
Scenario Three: Can we afford our current lifestyle when we move to assisted living?
Permission to spend.
This is perhaps the most important thing scenario planning can provide couples in this stage of life. Many feel as though they should ration their own comfort out of fear that the money will run out.
Scenario planning may help you paint the opposite picture.
Maybe you can stay in the community you love without question, even if your spouse suddenly transitions to a higher and more expensive level of care. Traveling, going out for dinner weekly, and paying for your granddaughter’s education may still be possible. By mapping out your options, you might realize that you can still leave a substantial legacy for your family or community, even in the worst-case scenario.
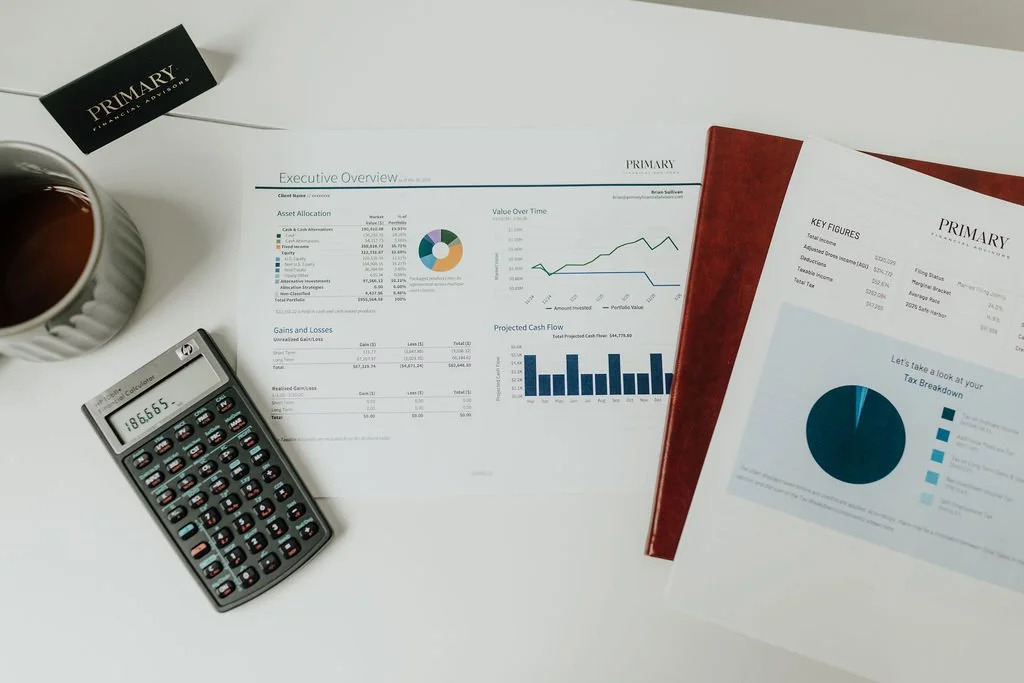
Why is scenario planning a tool for every stage of life?
Whether you are 55 and navigating the complexity of peak earning years or 70 and trying to make sure your resources last as long as you need them to, scenario planning answers the question that sits underneath almost every financial conversation we have:
Will I be okay?
The answer isn't always simple. But with the right scenarios modeled, the right variables stress-tested, and the right advisor walking you through the numbers, it is almost always clearer than you feared.
If scenario planning isn't already part of your financial plan, let's talk about what it might reveal for you. Click below to schedule a call with me.
Any opinions are those of Primary Financial Advisors and not necessarily those of Raymond James. The information has been obtained from sources considered to be reliable, but we do not guarantee that the foregoing material is accurate or complete.
Raymond James and its advisors do not offer tax advice. You should discuss any tax matters with the appropriate professional.
Certified Financial Planner Board of Standards Center for Financial Planning, Inc. owns and licenses the certification marks CFP® and CERTIFIED FINANCIAL PLANNER® in the United States to Certified Financial Planner Board of Standards, Inc., which authorizes individuals who successfully complete the organization's initial and ongoing certification requirements to use the certification marks.