
By Brian Sullivan, CFP® professional, Primary Financial Advisors
TL;DR: Not all financial plans are created equal. A truly comprehensive plan has two layers 1) what you can see in your plan and 2) the qualitative inputs that shape everything behind it.
Together they cover investments, retirement, tax strategy, estate planning, insurance, cash flow, and legacy. This post breaks down both layers and what to look for when evaluating whether your plan measures up.
A lot of financial professionals say they offer financial planning. But what does that actually mean?
As you read on, you'll get answers to the following questions:
What is a financial plan and what should it do?
What's the difference between the visible and invisible layers of a financial plan?
What are the core components that every plan should include?
What is scenario planning and why does it belong in a financial plan?
How often should a financial plan be updated?
What's the difference between a financial plan and investment management?
How do you know if your advisor is going deep enough?
How do you get started building a comprehensive financial plan?
What Is a Financial Plan, Really?
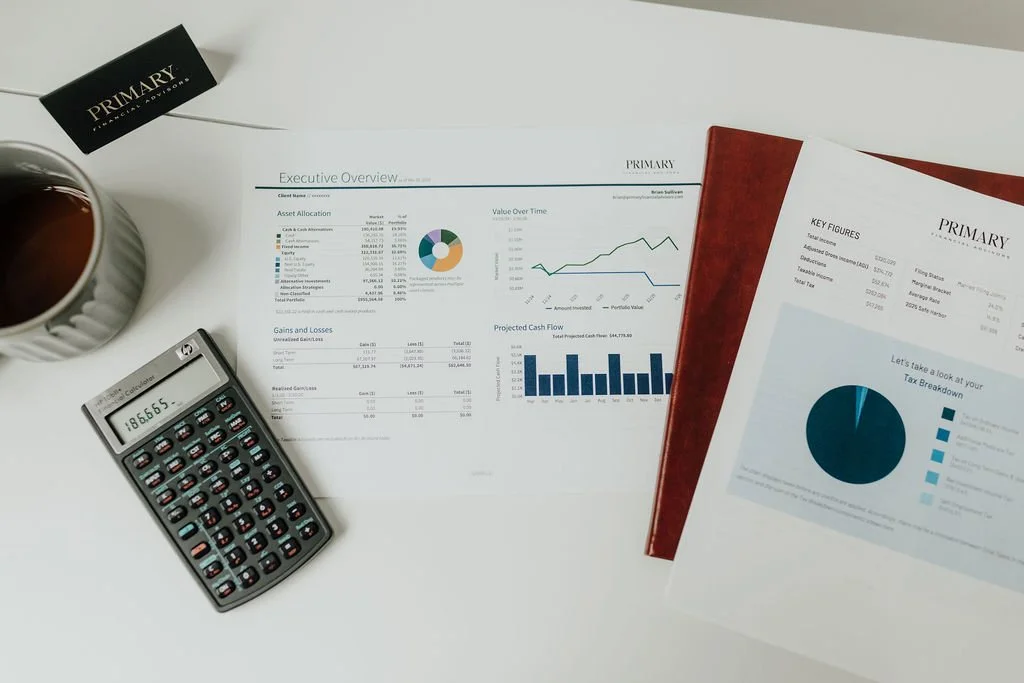
Most people think a financial plan is a spreadsheet, a printed document, or a portfolio review that happens once a year. It can be that, but it should be much more.
We build financial plans in a secure online portal that you can access anytime. It's a living, breathing document that gets updated constantly when markets shift, when your life changes, or when opportunities or challenges arise. It’s not something that gets handed to you once a year and then filed away.
But what you see in that portal is only part of the story. Behind every number is a set of conversations, questions, and considerations that don't show up on a screen, but they shape everything that does.
A truly comprehensive financial plan has an invisible and a visible layer. Here's what that means in practice.
The Invisible Layer of a Comprehensive Financial Plan
The invisible layer is where the unique aspects and details of your life are captured. These things should inform every number in the visible financial plan.
Your financial advisor will likely ask you a variety of questions in your first meetings and then gradually over time to understand you and how you live.
To help them create a comprehensive financial plan, the questions an advisor will ask will likely center around:
Your life goals and vision for the future. What do you want your life to look like now and in retirement?
Your values around wealth, legacy, and giving. Do you want to leave something behind for your children? Are there causes you care deeply about? How do you feel about transferring wealth during your lifetime versus at death? These conversations can influence your estate plan, your charitable giving strategy, and how your assets are ultimately structured and transferred.
Your relationship with risk. Not just how much risk you can afford to take, but how much you can live with on a day-to-day basis.
Your appetite for tax complexity. How proactive do you want to be when it comes to taxes? How comfortable are you with sophisticated strategies like Roth conversions, direct indexing, or donor-advised funds?
Your obligations to the people who depend on you. This is what drives your insurance strategy. Not a coverage calculator, but an honest conversation about what would happen to your family if something happened to you. Considerations for aging parents, children's education, blended family dynamics, and special needs dependents sit at the center of a comprehensive plan and affect everything from your cash flow to your estate strategy.
Your health and longevity expectations. How long do you expect to live? Are there health considerations that may affect your retirement timeline or long-term care needs? These aren't easy conversations. But they're essential to building a plan that's honest about the future rather than simply optimistic about it.
The Visible Layer of a Comprehensive Financial Plan
The visible layer is what lives in your plan and can be tracked, updated, and measured over time. This can include your investments, your retirement projections, your net worth, your cash flow, and the outputs of your tax, estate, and insurance strategies.
What Can You See in Your Financial Plan?
These are the quantitative components that live in your plan and get updated as your life and the markets evolve.
Charts and graphs to show you the performance of your investment portfolio.
Visuals to outline when you can retire based on your goals. It also outlines withdrawal strategies, required minimum distributions, healthcare costs, and Social Security benefits.
Different financial scenarios to show what might happen if you retire early, start your own business, buy your vacation home, or if you have a health event or an increased care needs. You can learn more about how we approach scenario planning here.
Your cash flow which looks at your income, your fixed and variable expenses, your savings rate, and your spending patterns. This detail can help you determine or update a budget. Your plan can include opportunities to optimize, including how to save more, spend more intentionally, and make sure your day-to-day financial decisions are aligned with your long-term goals.
The tax strategies in place and the savings they're generating
The estate planning documents you have, what they cover, and whether they're current
The insurance policies you hold, the coverage amounts, and whether any gaps exist
How Often Should a Financial Plan Be Updated?
A financial plan is not a set-it-and-forget-it document. Life changes. Markets change. Tax laws change. Your goals change.
At a minimum, your plan should be reviewed annually. But certain life events should trigger an immediate review:
A job change, promotion, or layoff
Marriage, divorce, or the birth of a child
The death of a spouse or family member
A significant inheritance or windfall
A business sale or major liquidity event
A health diagnosis, yours or a family member's
When you’re approaching retirement
At Primary Financial Advisors, we don't wait for our clients to call us. We check in with clients regularly. Because we know what’s important to them and what’s happing in their life we can bring ideas to them proactively, consistently, and with the full picture in mind.
What Is the Difference Between a Financial Plan and Investment Management?
This is one of the most important distinctions in personal finance — and one of the most misunderstood.
Investment management is one component of a financial plan. It's an important one. But a financial advisor who only manages your portfolio is like a doctor who only checks your blood pressure. They're doing something useful, but they're missing most of the picture.
A comprehensive financial plan integrates your investments with your tax strategy, your estate plan, your insurance coverage, your retirement timeline, and your life goals. Everything works together. Nothing exists in isolation.
That's also the difference between a financial advisor and a Personal CFO. You can learn more about what a Personal CFO does in this blog post.
How Do You Know If Your Advisor Is Going Deep Enough?
Here are a few questions worth asking:
Does your advisor meet with you more than once a year?
Do they bring ideas to you proactively, or do they wait for you to ask?
Does your plan address taxes, estate planning, and insurance — or just investments?
Do they ask about your life goals, your family, and your values — or just your risk tolerance?
Is your plan a living document that gets updated regularly, or a static report that sits in a drawer?
If the answers give you pause, it may be time for a second opinion. You can read more about what that might look like in this blog post.
How Do You Get Started With a Financial Planner?
Step 1: A conversation. At Primary Financial Advisors, we start every new relationship by asking one simple question: "How can we be helpful?" We want to understand what's important to to you in your life first.
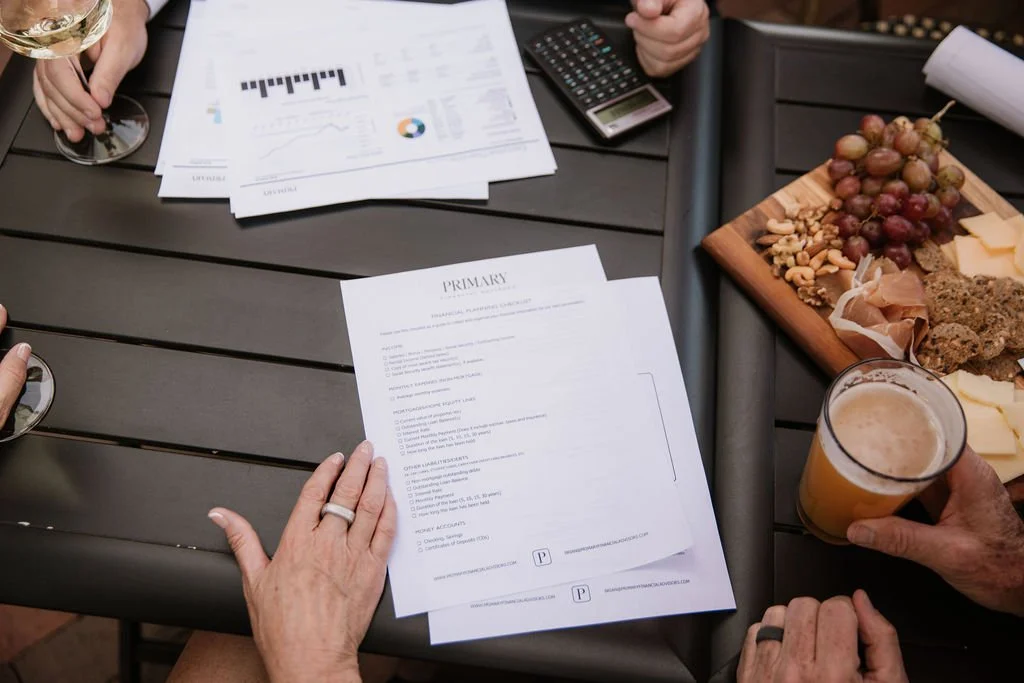
Step 2: After this initial conversation, we share our financial checklist with clients. This is when we start to talk about numbers. When they complete the checklist, most clients also send us statements and other financial data. This helps us create a comprehensive financial plan tailored to your specific situation.
Step 3: In our second meeting, we share the financial plan: the elements that exist in the online portal and our general recommendations and strategies. And this happens before contacts become clients. That’s because we believe finding a financial planner is a bit like dating. Seeing an advisor’s thinking and analysis early on can be a good way to make sure they are the right fit before you make a long-term commitment.
Over the long-term: When clients work with us, we have phone calls and meetings consistently over time, not just once a year, to make sure your plan stays aligned with your life as it evolves. And our company is called Primary Financial Advisors because we’re the first place that clients call – day or night – when they have questions about money. So we connect in-between scheduled meetings, too.
If you've been wondering whether your financial life is as organized, optimized, and intentional as it could be, let's find out together.
Reach out anytime to schedule a no-commitment 15-minute consultation.
Any opinions are those of Primary Financial Advisors and not necessarily those of Raymond James. The information has been obtained from sources considered to be reliable, but we do not guarantee that the foregoing material is accurate or complete.
Raymond James and its advisors do not offer tax advice. You should discuss any tax matters with the appropriate professional.
Certified Financial Planner Board of Standards Center for Financial Planning, Inc. owns and licenses the certification marks CFP® and CERTIFIED FINANCIAL PLANNER® in the United States to Certified Financial Planner Board of Standards, Inc., which authorizes individuals who successfully complete the organization's initial and ongoing certification requirements to use the certification marks.
